By Naser Ameen
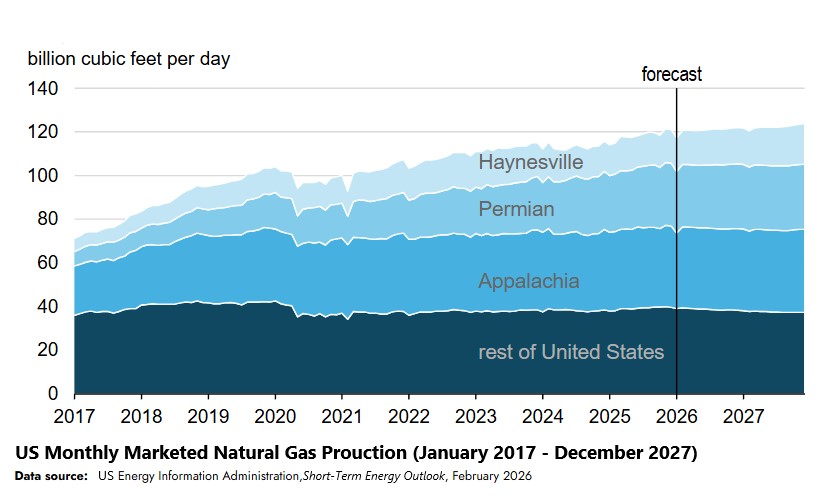
The US Energy Information Administration (EIA) forecasts that US natural gas marketed production will increase by 2% to average 120.8 bcf/d (3.42 x 10⁹ m3/d) in 2026 and then further increase to a record-high 122.3 bcf/d (3.46 x 10⁹ m3/d) in 2027. Around 69% of forecast production over the next two years comes from the Appalachia, Haynesville, and Permian regions.
US natural gas production growth will primarily come from the Appalachia region in the Northeast, the Permian region in western Texas and southeastern New Mexico, and the Haynesville region in eastern Texas and Louisiana.

Forecast production from the Haynesville region grows by 1.2 bcf/d (33.98 x 10⁶ m3/d) in 2026 and then by 1.6 bcf/d (45.3 x 10⁶ m3/d) in 2027, as natural gas prices remain relatively elevated through the forecast period. The EIA expects prices to rise from US$3.52 per MMBtu in 2025 to US$4.31/MMBtu in 2026 and to US$4.38/MMBtu in 2027, which allows drilling in the Haynesville region to remain economical, even with relatively deeper and more expensive well development. In addition, the Haynesville’s proximity to liquefied natural gas (LNG) export terminals and major industrial natural gas consumers along the US Gulf Coast draws operators to the region.
The Permian region contributes 1.4 bcf/d (39.64 x 10⁶ m3/d) to forecast production growth in 2026 and 0.6 bcf/d (16.99 x 10⁶ m3/d) in 2027. In the Permian region, growth in natural gas production is primarily the result of associated gas produced during oil production. The EIA estimates that oil-directed rig activity in the Permian will be relatively low as West Texas Intermediate prices fall from US$65/b in 2025 to average US$53/b in 2026 and then average US$49/b in 2027. Despite these lower prices, the EIA estimates that increases in gas-to-oil ratio (GOR) will drive natural gas production growth in the Permian region. The EIA expects the GOR to continue its steady increase in the Permian.
In recent years, the Appalachia region has provided the largest share of US domestic natural gas output, accounting for around 32% of US Lower 48 states production annually since 2016. Production growth has slowed in recent years because of pipeline capacity constraints. In June 2024, the Federal Energy Regulatory Commission authorized the Mountain Valley Pipeline to begin operations. With this new capacity addition, the EIA estimates that Appalachian production will grow slightly by 0.3 bcf/d (8.49 x 10⁶ m3/d) in 2026 and then by 0.5 bcf/d (14.15 x 10⁶ m3/d) in 2027.
About The Author: Naser Ameen is research analyst with the US Energy Information Administration.